
November 21, 2026 – A resurfaced warning from a Dutch central banker now meets live data. Dollar stablecoin supply has shrunk $13.6 billion this month, and the ECB wants new reserve rules.
In Summary
The Sleijpen warning recirculated on November 20 dates from an interview published on November 17, 2025.
The new policy signal is the ECB’s November 2026 call to swap MiCA deposit floors for liquidity rules.
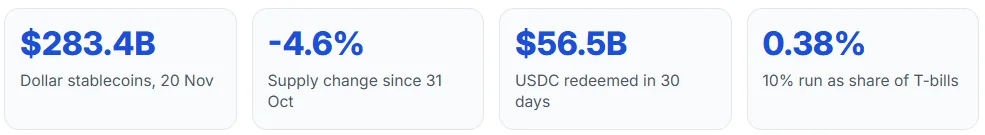
Dollar stablecoin supply fell 4.6% to $283.4 billion between October 31 and November 20.
A 10% run would require $28.3 billion of bill sales, or 0.38% of bills outstanding, by Catenaa estimates.
The sharper risks sit in bank deposits, money funds and repo, where stress could hit within hours.
Stablecoin runs are back on central bankers’ agenda. On November 20, crypto news sites ran a warning from Olaf Sleijpen. He heads the Dutch central bank and sits on the ECB’s Governing Council. However, his comments first appeared in an interview published on November 17, 2025, De Nederlandsche Bank records show. So the warning is a year old. Even so, fresh data now give it real weight.
What Sleijpen actually said
Sleijpen said US stablecoins “will become systemically relevant at a certain point” if growth continued. In a run, he warned, issuers might have to sell reserve assets fast. The ECB would then “probably have to rethink monetary policy.” Yet he did not know whether that meant higher or lower rates. Instead, he said financial stability tools should act first.
The new ECB stance on stablecoin runs
The truly new signal came two days earlier. In its November 2026 Financial Stability Review, the ECB backed changes to the EU’s MiCA rulebook. It said the EU could drop minimum bank deposit rules for stablecoin issuers. Minimum liquidity rules for reserve assets would take their place. The ECB said this could cut contagion channels between banks and stablecoins.
Today, MiCA requires e-money token issuers to keep at least 30% of reserves in bank deposits. For significant tokens, the floor rises to 60%. Consequently, a large run could drain deposits from a few European banks very quickly.

A live stress signal
Market data show why the issue matters now. The supply of dollar stablecoins fell to $283.4 billion on November 20, DefiLlama data show. That is $13.6 billion, or 4.6%, below the October 31 level. It also sits 9.4% under the May 17 peak of $312.9 billion.
Circle’s USDC shows how fast money moves. Over 30 days to November 19, Circle issued $52.9 billion and redeemed $56.5 billion, its transparency page shows. Gross redemptions equalled 84% of USDC’s $67.3 billion supply. Still, reserves of $67.6 billion exceeded the tokens in circulation.
Tether’s USDT remains the largest token, at $174.5 billion. USDC ranks second, at $68.7 billion. Together, the two hold about 86% of the dollar market, so their reserves matter most in any run.


A simple redemption stress test
Catenaa built a simple test that links redemptions to sales of US Treasury bills. It assumes issuers meet every redemption by selling bills. A 10% run on dollar stablecoins would then require $28.3 billion of sales. That equals 0.38% of the $7.38 trillion in bills outstanding on October 31, per Treasury data. Even a 25% run stays under 1%.
So the bill market looks deep enough to absorb modest stablecoin runs. The pressure points lie elsewhere. Forced selling could hit a few money funds and repo desks within hours. Meanwhile, bank deposits that back reserves could vanish just as fast.
That second channel matters most for policy. When issuers pull deposits, the banks lose cheap funding. They may then pay more for market money, and that cost feeds into loan rates. This is how a crypto run could reach the economy and, in time, rate decisions.

Why the euro area still cares
Euro stablecoins are still tiny, at about $0.8 billion. That is under 0.3% of the market. Therefore, the main euro area risk is indirect. Dollar tokens could pull savings from euro deposits and weaken bank lending. The ECB has also raised its deposit rate twice this year, to 2.50%. A sudden run could complicate that path.
For now, no central bank has moved rates because of stablecoin runs. Still, November’s shrinking supply offers a small, live test of Sleijpen’s scenario.