
October 18, 2026 – US venture funding hit a record $515.8bn through the third quarter. However, the week to 16 October produced just two rounds above $200m, and Modal Labs took 45 percent of the top ten.
In Summary
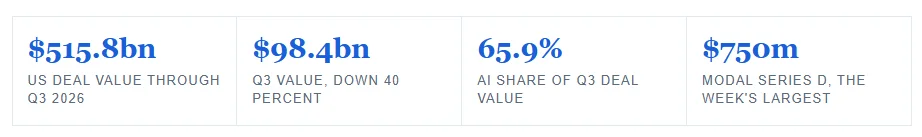
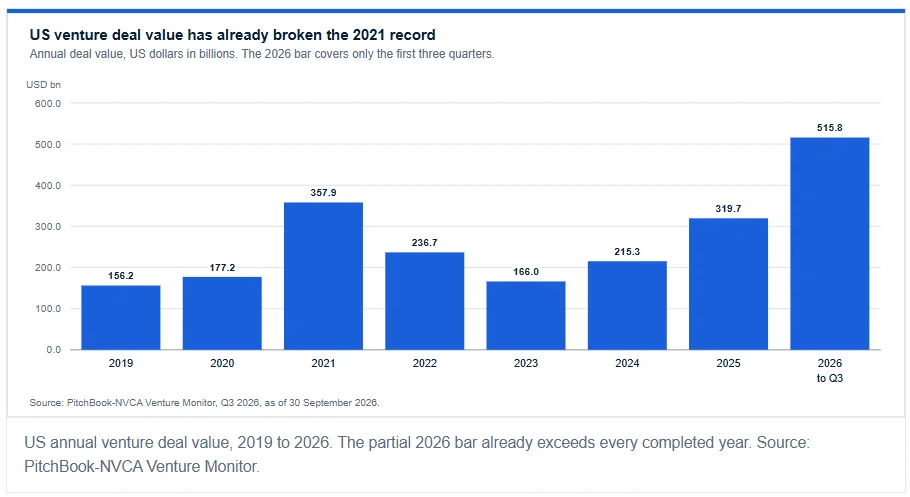
US venture deal value reached $515.8bn through the third quarter of 2026, roughly 44 percent above 2021’s full-year record.
Third-quarter value fell to $98.4bn, about 40 percent below the second quarter, even though an estimated 5,012 deals closed.
Rounds of $100m or more were about 5 percent of deal count but 75 percent of third-quarter value.
Modal Labs raised $750m led by Accel at a $15.75bn valuation, five times the 2026 median Series D-plus deal size.
ICON raised $200m co-led by Baillie Gifford and BlackRock, and Labelbox raised more than $100m at a $1.25bn pre-money valuation.
Venture funding stayed heavy in the week to 16 October 2026. However, it reached fewer companies. Only two US rounds cleared $200m. Modal Labs alone raised $750m, which equals 45.3 percent of the top ten by value, on Catenaa calculations.
That pattern now defines the market. Capital keeps flowing, but it pools around a handful of names. The quarterly data tells the same story.
Record venture funding, thinning at the top
US deal value reached $515.8bn across an estimated 14,199 deals through the third quarter. Therefore, 2026 already beats 2021, the previous record year, by roughly 44 percent. However, the momentum faded as the year went on.
Third-quarter value fell to $98.4bn, down about 40 percent from the second quarter. Deal count barely moved. An estimated 5,012 deals closed, the second-highest quarterly count on record. In short, the dollars shrank while the activity held.
Concentration explains the gap. Rounds of $100m or more made up about 5 percent of deal count. Nevertheless, they absorbed 75 percent of third-quarter value. The quarter’s biggest single deal shows the scale. Databricks closed $5bn of strategic funding at a $190bn valuation in August.
AI still sets the price
Artificial intelligence took 65.9 percent of third-quarter deal value. It fell from 88.4 percent in the first quarter. By contrast, its share of deal count held near 45 percent all year.
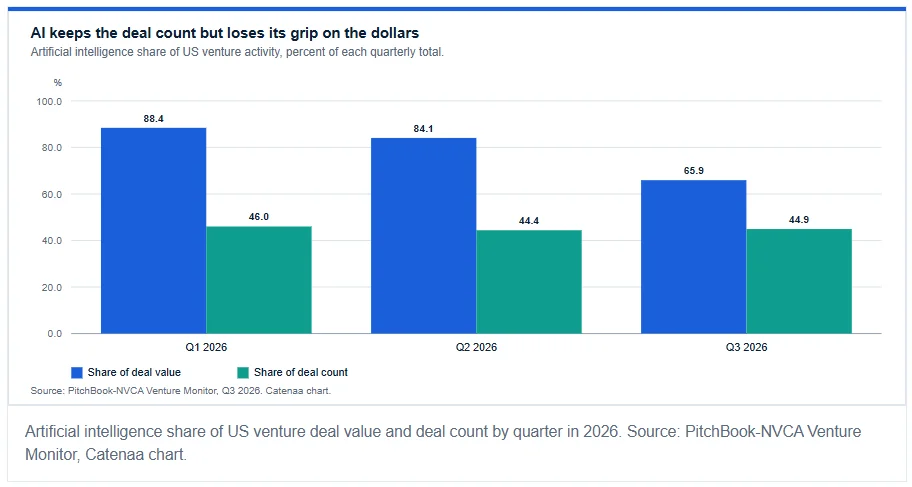
So the retreat is narrow. Frontier-lab megadeals tapered off, yet AI companies still win almost half of all rounds.
Modal, ICON and Labelbox led the week
Accel led Modal’s round at a $15.75bn post-money valuation. The company says its run rate passed $1bn and revenue grew more than 15 times year over year. Usage tripled since its Series C five months earlier.
For scale, the 2026 median Series D-plus deal is $150m. Modal’s round is therefore five times that median, by Catenaa calculations.
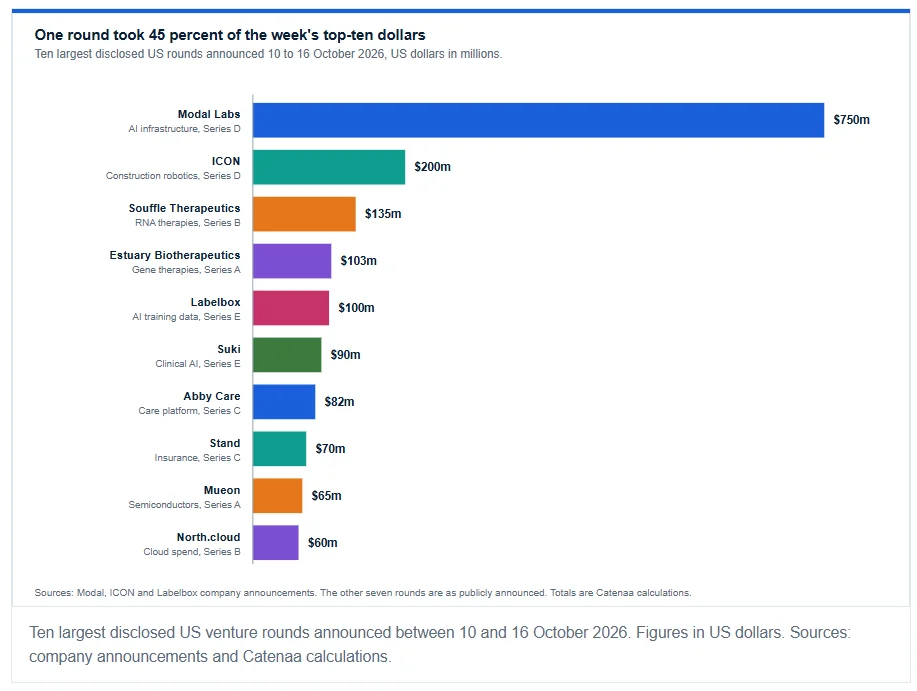
ICON took second place. The robotics builder raised $200m co-led by Baillie Gifford and BlackRock. It says it is on pace for four times revenue growth this year and has passed 270 printed buildings.
Labelbox then added more than $100m at a $1.25bn pre-money valuation, led by Infinitum Partners. Notably, the company says it reached profitability this year and grew more than five times.
What the valuation data signals
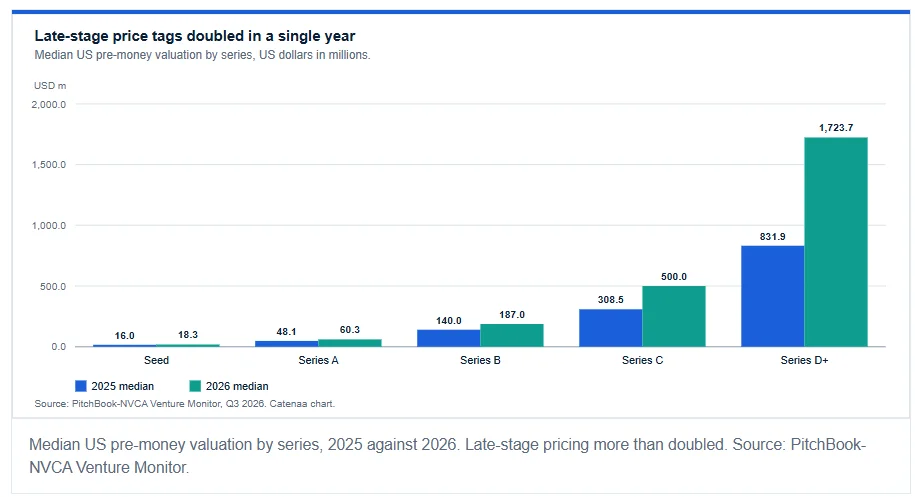
Median late-stage pricing moved sharply. Series D-plus pre-money medians rose from $831.9m in 2025 to $1.72bn in 2026. Seed medians barely budged.
Exits remain the weak link. The Venture Monitor notes that both large AI labs are delaying their listings. Consequently, paper gains keep building while cash returns lag.
New company formation still looks healthy. An estimated 8,625 first-time financings closed through September, already past the 2021 full-year record of 8,507. Therefore, the funnel is widening at the bottom even as the top narrows.
Some investors told the report’s authors they now hunt sectors insulated from AI disruption. ICON’s robotics round fits that brief. So does Labelbox, which sells into AI builders rather than competing with them.