
November 11, 2026 – An amended filing shows about $84.6 billion of net new money from the listing and a $26 billion partner deal. Both sit against $900.9 billion of compute commitments.
In Summary
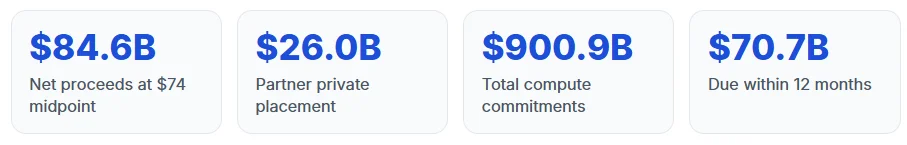
Anthropic expects about $84.6 billion of net proceeds from the IPO and a $26 billion private placement.
Selling holders get about $1.75 billion at the midpoint. Anthropic receives none of that money.
Compute and lease commitments total about $900.9 billion, with $451.6 billion due before 2031.
Cash, short-term investments and new proceeds cover roughly 48% of the pre-2031 bill, by Catenaa’s math.
Anthropic filed a second amended S-1 with the SEC on Nov. 10, and it sharpens the Anthropic IPO math. The filing sets a price range of $70 to $78 per share. It also shows how much money actually reaches the company.
How much cash does the Anthropic IPO raise?
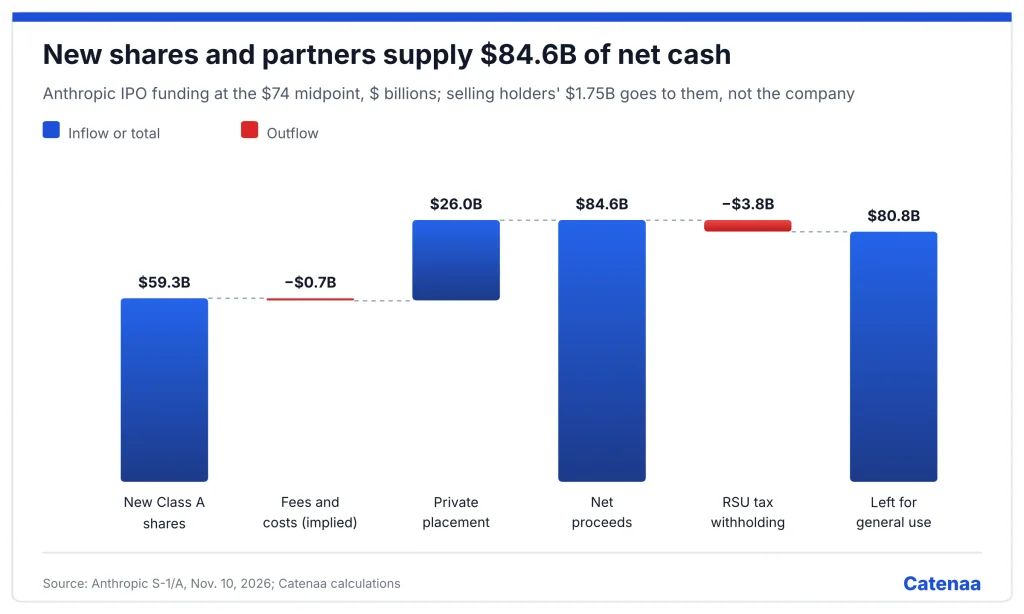
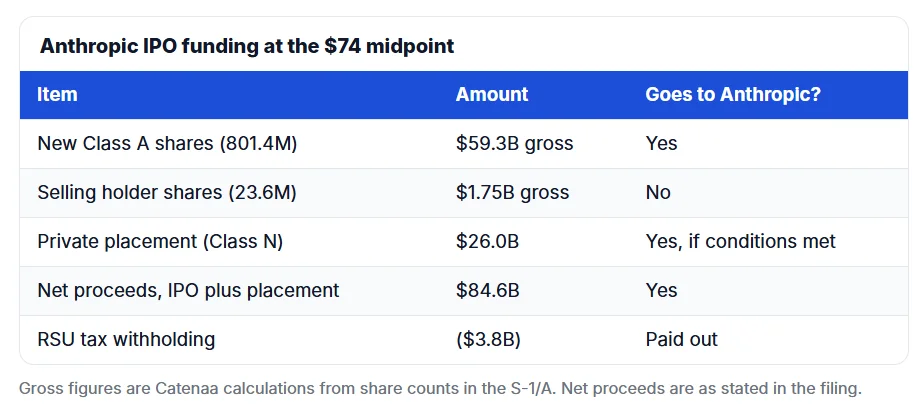
The company plans to sell 801,351,354 new Class A shares. Selling holders will add 23,648,646 shares. At the $74 midpoint, new shares raise about $59.3 billion, by Catenaa’s math. Existing holders sell about $1.75 billion more.
That price also sets the headline value. About 13.09 billion shares will be outstanding after the deal. At $74 each, that implies a market value near $968 billion, by Catenaa’s math.
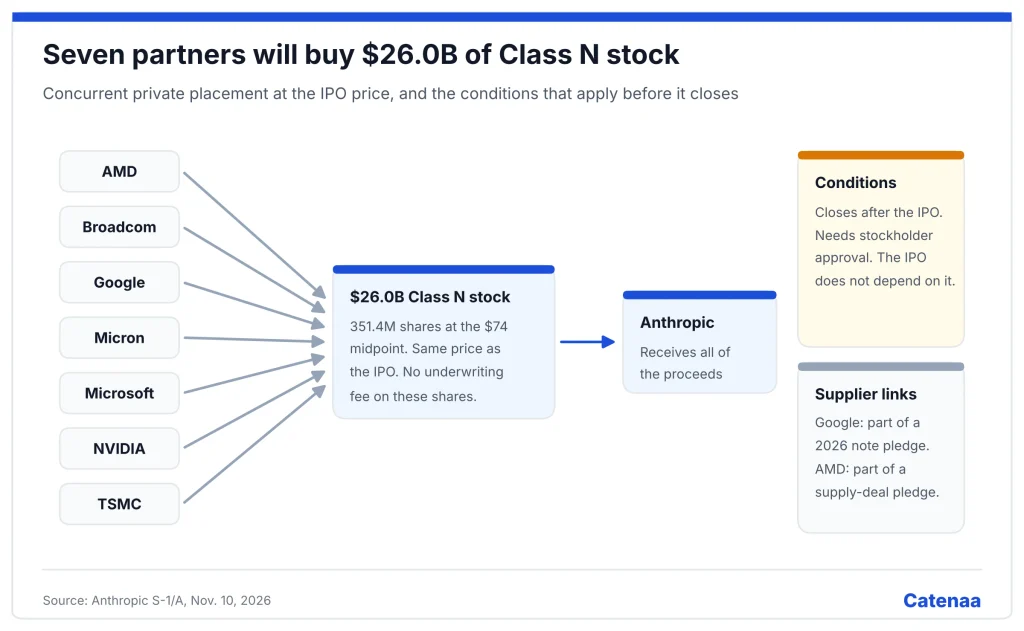
Anthropic gets none of the secondary cash. Instead, it keeps the new share money plus a $26 billion private placement. Seven partners will buy Class N shares at the IPO price: AMD, Broadcom, Google, Micron, Microsoft, NVIDIA and TSMC.
Together, the prospectus puts net proceeds at about $84.6 billion. That rises to roughly $93.7 billion if banks take their full option on 123.75 million extra shares.
Strings attached to the $26 billion
The placement closes only after the IPO. It also needs stockholder approval and other conditions. However, the IPO itself does not depend on it.
Several buyers are also suppliers. Google’s share funds part of an investment it had already pledged under a 2026 note deal. AMD’s share meets part of a stock pledge tied to a hardware supply pact.
Insiders are circling, too. Board members and related entities have shown interest in buying up to $303 million of IPO shares. Those signals are not binding.
Anthropic will also spend about $3.8 billion of proceeds on tax withholding for an RSU settlement. That leaves roughly $80.8 billion for general use, by Catenaa’s math.
The $900.9 billion question
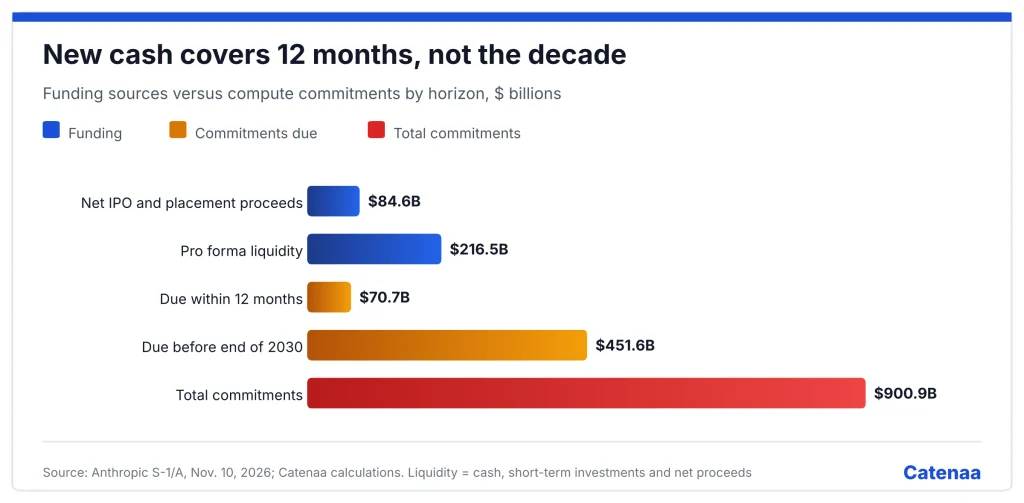
The bigger number sits in the risk section. As of and after Sept. 30, Anthropic has signed purchase and lease deals worth about $900.9 billion. Nearly all of it covers compute and infrastructure. A large part relates to Anthropic Direct, where it leases chips and hosts them in dedicated sites.
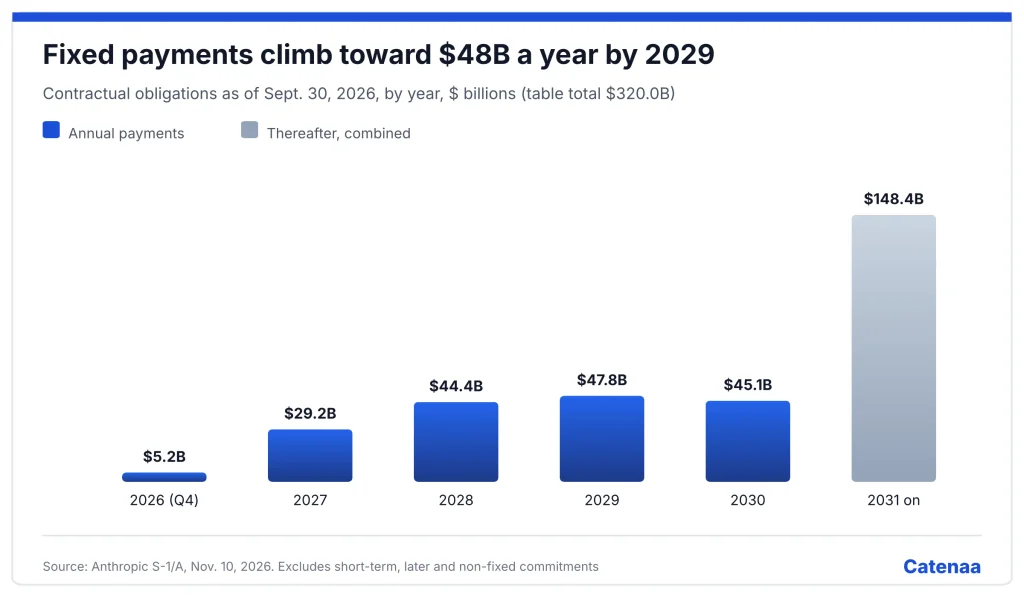
Timing matters more than the total. About $70.7 billion falls due within 12 months of Sept. 30. Roughly $451.6 billion lands before the end of 2030. Most of the rest runs from 2031 to 2045.
On that schedule, the Anthropic IPO money looks large but finite. It covers the next 12 months about 1.2 times. Yet it meets under a fifth of the bill due by 2030.
Still, Anthropic is not starting from zero. It held $95.6 billion of cash and $36.3 billion of short-term investments on Sept. 30. Add the new money, and liquidity reaches about $216.5 billion, or 48% of the pre-2031 bill.
Revenue has to carry the rest
Therefore, sales must close the gap. Here the trend helps. Revenue reached $33.2 billion in the first nine months of 2026, up from $2.5 billion a year earlier. Operations also produced $6.6 billion of cash.
There is some slack, too. About $186.2 billion of the deals carry exit rights or conditions. Moreover, the total leaves out other deals with no fixed price, which Anthropic puts at $150 billion to $175 billion.
What to watch
The final price will shift the math. Each $1 move in the IPO price changes net proceeds by about $793 million. Investors should also track the stockholder vote on the placement.
For now, the EDGAR record tells a clear story. The Anthropic IPO is large, but compute costs are larger. Cash flow, not the IPO, will decide whether the plan holds.
Editorial note: This article is for information only and is not investment advice. Figures come from the primary sources listed above. Figures marked “by Catenaa’s math” and chart values labelled as Catenaa calculations are derived by Catenaa from those sources and may differ slightly from company figures because of rounding.