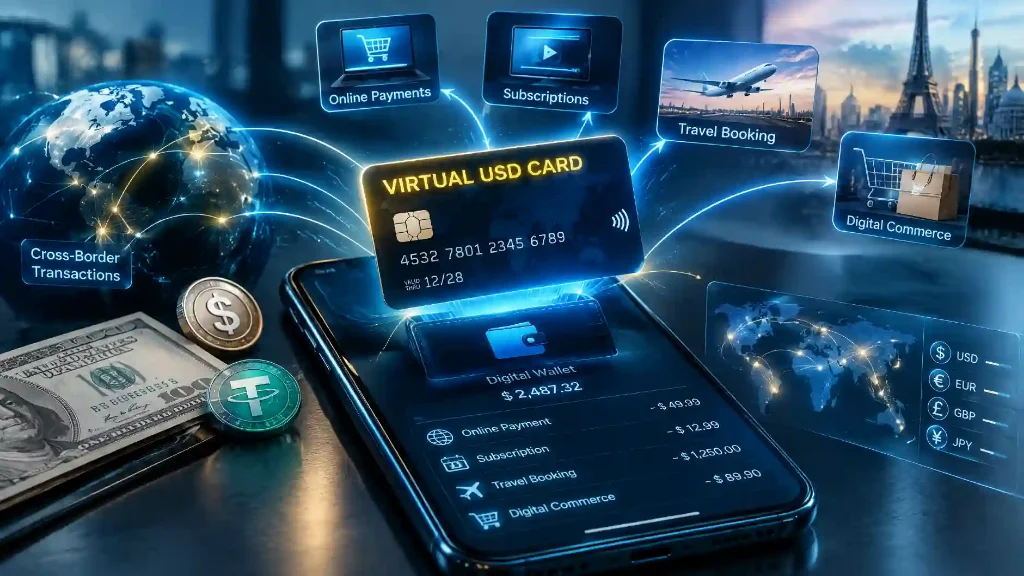

Catenaa, Sunday, September 27, 2026- Digital wallet provider Zorion has launched virtual USD cards, allowing eligible users to spend their wallet balances online without first withdrawing funds to a local bank account.
The Panama City-based company announced the service September 21 as part of a broader move from cross-border money transfers toward everyday payments.
Users can fund a Zorion balance and create a USD-denominated virtual card for online purchases, according to the company.
The card is intended for international subscriptions, travel bookings, advertising platforms and other online services that may not readily accept local payment methods.
Zorion already allows users to hold a digital dollar balance, transfer funds between users and withdraw money to supported local bank accounts.
Its website describes the underlying balance as USDT-based, allowing customers to fund accounts using cryptocurrency and supported local payment methods.
The addition of a virtual card gives users another way to use those balances without converting them back through conventional banking channels.
Zorion said card issuance can be completed within the platform after users complete the required verification process.
Its current help documentation lists a one-time $1 card issuance fee and says there are no monthly card fees.
The minimum card top-up is $5 and the maximum is $10,000, according to Zorion’s published support information.
Funds are transferred from the user’s existing wallet balance to the card, allowing top-ups without a separate external transfer.
Zorion’s help pages currently say one card can be issued per account.
That differs from the September 21 announcement, which described support for issuing multiple cards.
The company did not explain the discrepancy or whether multi-card issuance is being introduced gradually across different markets.
Card availability is also subject to jurisdiction, customer eligibility and know-your-customer requirements.
Zorion said issuance is handled through a card program partner holding relevant licences in the jurisdictions where the service is offered.
The company did not name that partner in its announcement.
Zorion’s website describes the product as a standard virtual card operating through established card-payment networks.
The company markets it particularly toward users in countries where locally issued cards can face difficulties with international websites or dollar-denominated services.
Its current consumer pages place a strong emphasis on Indonesia.
The platform lists Indonesian bank transfers, QRIS and local e-wallet services among supported methods for moving money into or out of a Zorion account.
That gives the card a different role from a conventional credit product.
Users are spending funds already placed in their Zorion balance rather than borrowing against a credit line.
Zorion also restricts several categories of card transactions.
Its published rules prohibit using the virtual card for cryptocurrency and investment purchases, foreign exchange trading accounts, gambling, cash withdrawals, gift cards and person-to-person money transfers.
The company says declined transactions may carry a fee and repeated prohibited transactions can result in card closure.
Those restrictions illustrate how virtual crypto-linked cards can connect blockchain-based balances with conventional payment networks without making every type of financial transaction available through the card itself.
The product also addresses a recurring problem for users receiving income or holding value digitally but lacking reliable access to internationally accepted payment cards.
Freelancers, online workers and users of digital services may be able to receive or hold dollar-linked assets while still encountering difficulty paying foreign merchants.
Virtual cards attempt to bridge that gap by turning an existing digital balance into credentials accepted by conventional online checkout systems.
Zorion said it plans to add support for Apple Pay and Google Pay as the card program develops.
The September announcement also listed card freeze and unfreeze controls among planned additions, although parts of Zorion’s current website already describe instant card-freezing capabilities.
That suggests some features may already be appearing for selected users or markets.
The expansion comes as digital wallets increasingly combine stablecoins, local payment methods and conventional card infrastructure within a single account.
For providers, cards can turn a wallet primarily used for transfers into a product customers interact with more frequently.
For users, the attraction is the ability to move from receiving or holding digital dollars directly into spending them.
The model still depends on conventional card infrastructure and regulated issuance partners even when the underlying wallet uses cryptocurrency.
Zorion acknowledges that distinction by limiting availability to jurisdictions where its card partner is authorized to operate.
The launch therefore represents less of a replacement for traditional payment networks than another connection between them and digital-dollar wallets.
For Zorion, that connection expands the wallet from moving money across borders to giving users a way to spend the same balance online.




