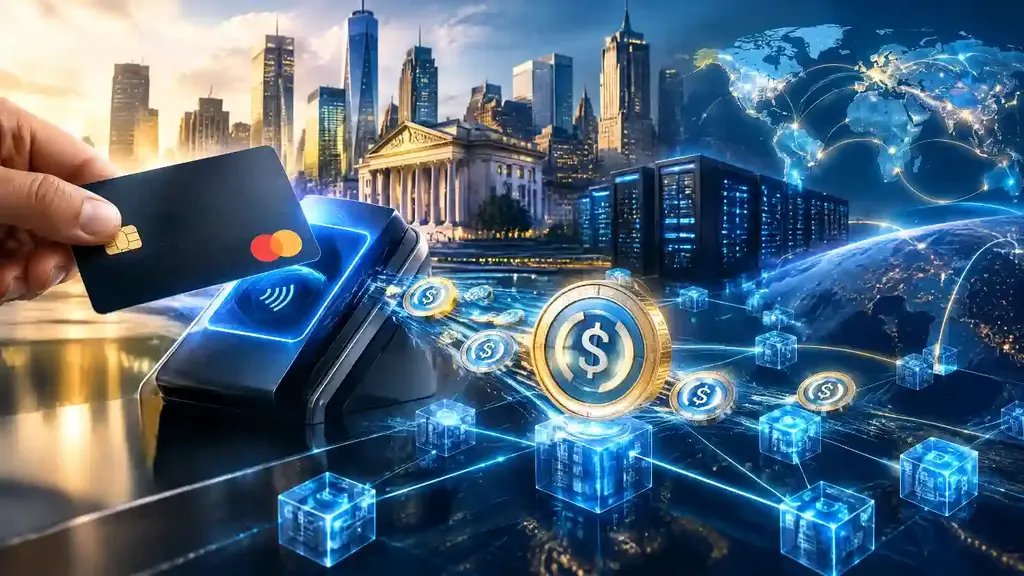

Catenaa, Tuesday, September 22, 2026- SoFi Bank has begun settling debit and credit card transactions with its SoFiUSD stablecoin across Mastercard’s global payments network, moving its entire card program toward blockchain settlement.
The program is expected to process more than $25 billion in annualized volume, according to SoFi.
The company said it is the first US nationally chartered bank to take stablecoin settlement live across Mastercard’s global payments network.
Transactions are already being settled on blockchain rails using SoFiUSD, a dollar-backed stablecoin issued by SoFi Bank.
The move takes stablecoins deeper into mainstream payment infrastructure. Rather than being used mainly for crypto trading or transfers between digital wallets, SoFiUSD is now being used behind conventional debit and credit card transactions.
Consumers can continue paying with their cards as usual.
Merchants also do not need to receive SoFiUSD, maintain crypto wallets or change their existing payment systems.
Instead, the stablecoin operates within the settlement process between financial institutions.
SoFi said merchants using its Big Business Banking platform can receive settlement funds directly into a SoFi Bank account. Those funds can then be converted to cash around the clock without a withdrawal charge.
The companies announced their initial partnership in March, when they said SoFiUSD would become a settlement option across Mastercard’s network.
That plan has now moved from testing and integration into a live production environment.
SoFiUSD was launched in December 2025 and later became available to customers through the SoFi banking application.
The stablecoin is issued by SoFi Bank, a nationally chartered US bank regulated by the Office of the Comptroller of the Currency.
SoFi says each token can be redeemed for one US dollar and is backed mainly by cash reserves.
The company also states that SoFiUSD itself is not a bank deposit and is not insured by the Federal Deposit Insurance Corp.
SoFiUSD operates on Ethereum and Solana, giving users access to two of the largest blockchain ecosystems supporting stablecoin transactions.
Mastercard has been expanding its own stablecoin settlement system beyond SoFiUSD.
In June, the payments company announced support for regulated stablecoins including Circle’s USDC, PayPal USD, Ripple’s RLUSD and Paxos-issued stablecoins.
Its settlement framework is designed to operate across blockchain networks including Arbitrum, Base, Canton, Ethereum, Polygon, Solana, Tempo and the XRP Ledger.
The infrastructure is intended to give participating issuers and payment companies more flexibility over when transactions are settled.
Traditional card settlement often depends on banking hours and financial intermediaries. Blockchain settlement can operate continuously, including weekends and holidays.
SoFi’s launch illustrates an important shift in how financial companies are approaching stablecoins.
The technology does not have to replace familiar payment methods for consumers.
Instead, blockchain networks can operate behind existing payment systems, where customers may never directly interact with a stablecoin.
That distinction could matter for adoption.
Businesses may be reluctant to redesign payment systems or manage digital assets directly. A settlement model can give them access to blockchain-based money movement without requiring those changes.
For financial institutions, continuous settlement could reduce delays between card transactions and the movement of funds.
It may also improve liquidity management because institutions can move settlement funds outside normal banking hours.
The scale of SoFi’s program makes the experiment notable.
More than $25 billion in expected annualized card volume would put a large amount of conventional payment activity through infrastructure that uses a bank-issued digital dollar for settlement.
The figure, however, is an expected annualized volume rather than a completed transaction total.
SoFi is also discussing stablecoin settlement arrangements with large US merchants, including multinational retailers and technology service platforms. The company has not identified those businesses.
Another possible expansion could come through Galileo, SoFi’s financial technology platform.
The companies previously said Galileo could allow other issuing banks to choose SoFiUSD for Mastercard settlement, potentially extending the model beyond SoFi’s own customers.
SoFi CEO Anthony Noto said the structure was designed so merchants would not need to hold stablecoins or build blockchain infrastructure.
He said businesses could instead receive settlement funds through ordinary SoFi Bank accounts while gaining faster access to money.
Mastercard Global Head of Digital Commercialization Sherri Haymond described the launch as a move from stablecoin experimentation into practical payment infrastructure.
Mastercard has increasingly positioned regulated stablecoins as an additional settlement option rather than a replacement for its existing payments network.
That approach allows conventional cards, bank accounts and merchant systems to remain in place while blockchain technology operates beneath parts of the settlement process.
SoFi and Mastercard are now examining additional uses for SoFiUSD, including cross-border payments and remittances.
Those markets could become another test of whether regulated stablecoins can reduce settlement delays while operating within existing financial systems.
For now, the more immediate development is occurring behind ordinary card payments.
A customer can still use a familiar Mastercard debit or credit card, while the institutions handling that payment can settle part of the transaction using a dollar-backed token on blockchain infrastructure.
That makes the SoFi rollout less about turning cardholders into crypto users and more about changing the financial machinery operating behind the card.
The launch could therefore become an important test of whether stablecoins can move from crypto markets into the routine settlement systems used by banks, payment networks and merchants.
Verification: SoFi’s September 22 announcement confirms the live rollout, its full card-program migration and the expected annualized volume above $25 billion. Mastercard’s earlier announcements confirm the March partnership and its wider multichain stablecoin settlement program.




