

September 26, 2026 – Bitcoin, ether, Solana and XRP have all posted double-digit quarterly gains. Fund flows turned positive after the Federal Reserve decision.
In Summary
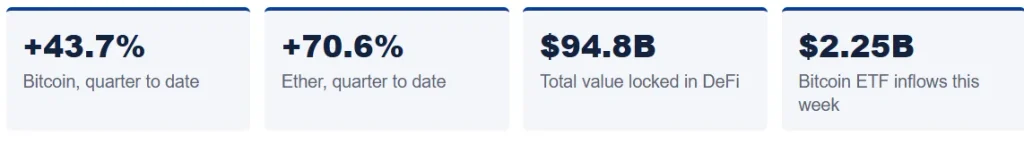
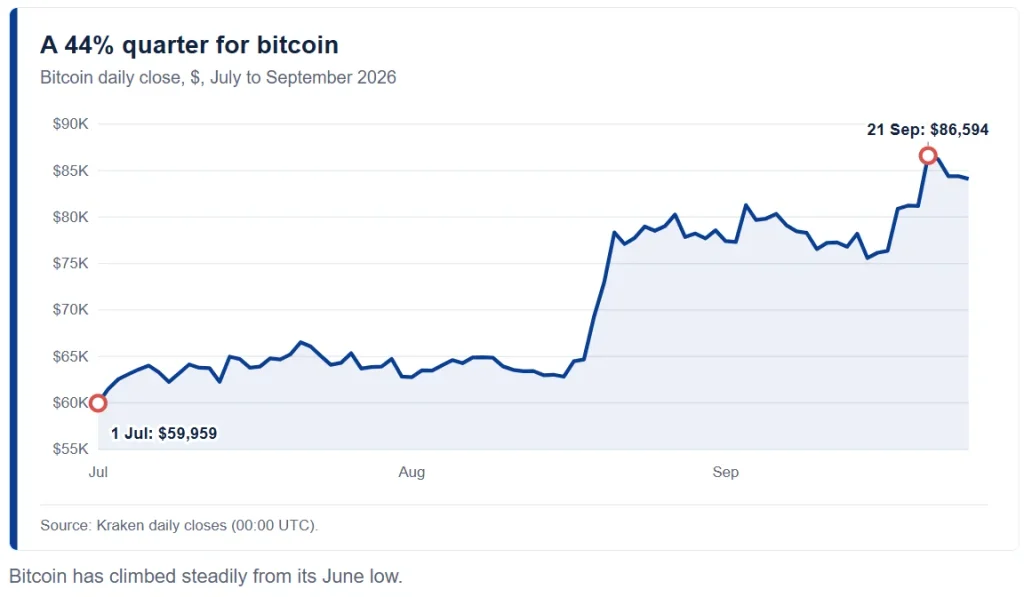
Bitcoin trades near $84,100, about 44% higher than at the end of June.
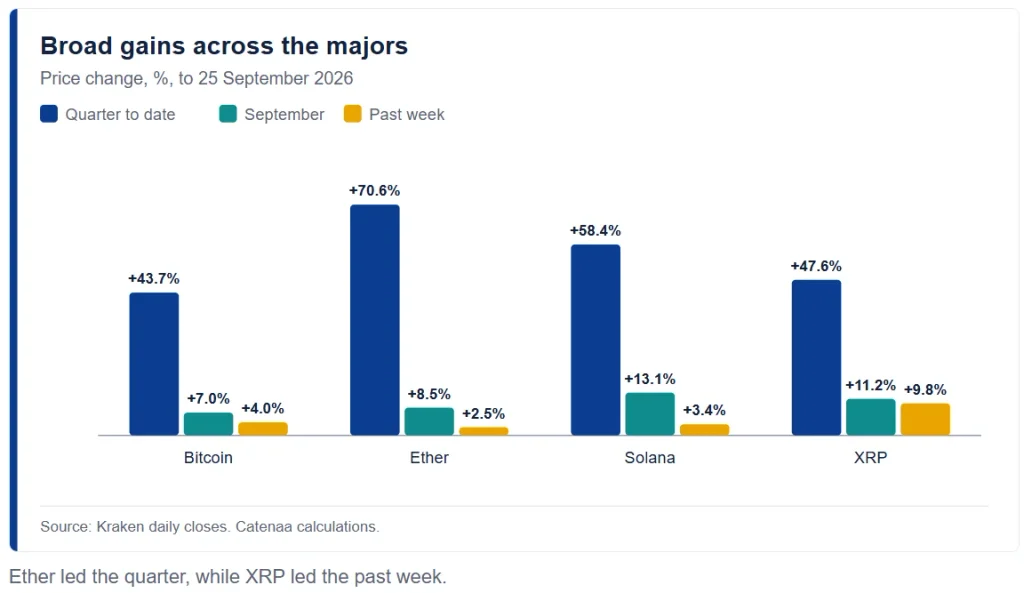
Ether has gained about 71% over the quarter, the strongest of the major tokens.
Solana is up about 58% and XRP about 48% since the end of June.
Spot bitcoin ETFs drew about $2.25 billion between 21 and 24 September.
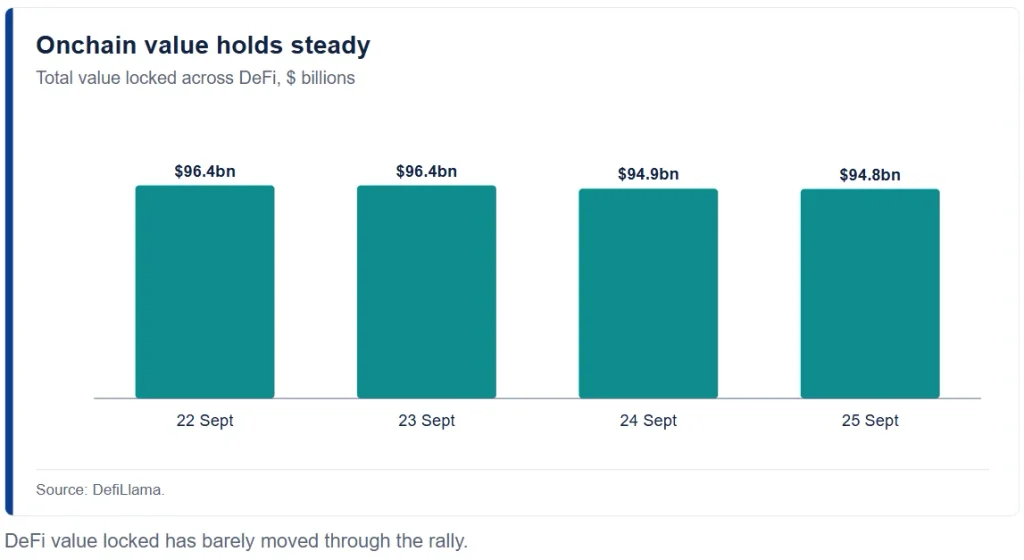
Total value locked across DeFi stands near $94.8 billion, down about 2% from Tuesday.
The crypto market is closing a strong quarter. Bitcoin trades near $84,100, up about 44% since the end of June, Kraken data show. Ether has done even better, with a gain of roughly 71%.
September has added to those returns. Bitcoin is up about 7% this month, while ether has gained 8.5%. Solana leads the majors with a rise near 13%.
Yet the mood is calmer than the numbers suggest. Prices have drifted lower since Monday’s peak. Traders are squaring books before quarter end.
How the Crypto Market Performed
Every major token has gained ground since June. Ether rose from about $1,570 to $2,678, exchange data show. That is the strongest run among the four largest assets.
Solana climbed about 58% over the quarter, to $116.55. XRP added roughly 48%, ending the week near $1.53. Bitcoin’s 44% gain looks modest by comparison.
The weekly picture is narrower. XRP rose 9.8% in the week to 25 September. Bitcoin managed 4.0%, ether 2.5% and Solana 3.4%. Gains therefore slowed as the quarter drew to a close.
The Fed Decision Reset Sentiment
Policy set the tone this month. The Federal Reserve raised its target range to 3.75% to 4.00% on 16 September. Crypto prices fell into that meeting, then rallied hard afterwards.
Bitcoin bottomed near $75,585 on 15 September. It then climbed to $86,593 by 21 September, its highest close since January. Buyers treated the decision as the end of uncertainty.
Fund flows tell the same story. Spot bitcoin ETFs took about $2.25 billion between Monday and Thursday, Farside data show. Before the meeting, those funds shed $746 million in two sessions.
DeFi Activity Holds Steady
Onchain activity has not kept pace with prices. Total value locked across DeFi stands near $94.8 billion, DefiLlama figures show. That is down about 2% from Tuesday.
Stable value locked suggests limited leverage build-up. Lending protocols and decentralised exchanges have not seen the frantic growth of past cycles. Consequently, forced unwinds look less likely than in 2021 or 2022.
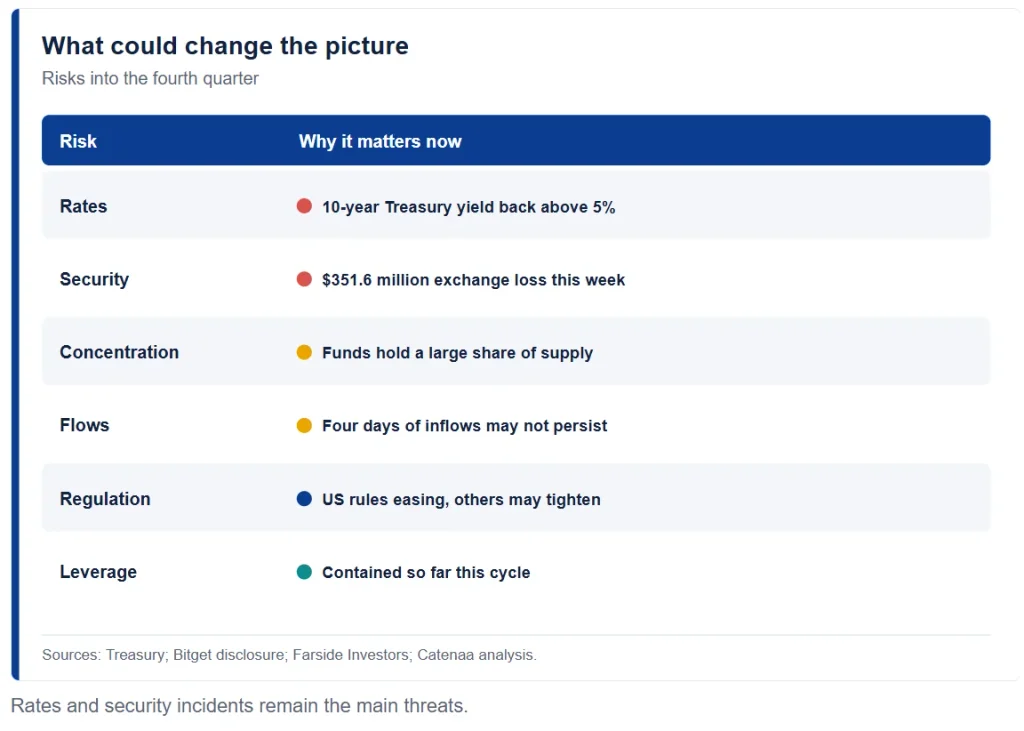
Security incidents remain the main tail risk. One exchange reported a $351.6 million hot wallet loss this week. Markets shrugged, though such events can shift sentiment quickly.
Stablecoins offer another gauge. Supply across all issuers sits near $312 billion, close to where it started the month. Steady supply usually signals patient money rather than speculation.
What the Quarter Reveals
Three patterns stand out. First, altcoins with fund products attracted the most enthusiasm. Ether and Solana both benefited from ETF launches and steady inflows.
Second, the rally lacked retail froth. Trading volumes rose, yet leverage stayed contained compared with previous bull phases. That mix usually produces slower but steadier advances.
Third, correlations with equities remain loose. The Nasdaq set a record on 21 September, then eased. Crypto followed that pattern only in part.
That looseness helps portfolio builders. An asset that moves on its own drivers adds diversification. Investors still treat crypto as a risk asset, however, when markets fall together.
What Could Break the Trend
Rates present the clearest threat. The 10-year Treasury yield has pushed back above 5% after this week’s strong business surveys. Higher real yields historically weigh on assets without cash flows.
Regulatory surprises cut both ways. American agencies have opened doors for tokenised trading and collateral this month. A reversal elsewhere, however, could dent confidence.
Concentration is the quieter risk. A handful of funds now hold a large share of tradeable supply. Redemptions at that scale would test market depth.
Exchange risk belongs on the same list. This week showed that even large venues lose funds. Traders who keep balances on one platform carry that risk directly.
What to Watch Next Week
The calendar starts with quarter-end flows on Wednesday. Rebalancing can distort prices for a session or two. Afterwards, attention returns to macro data and the next round of inflation figures.
Fund flows deserve equal attention. Four straight days of bitcoin inflows suggest institutional demand, not retail chasing. Whether that continues into October will shape the next leg.
Earnings season adds a further test. Crypto-linked companies report in late October, and their numbers reveal real activity. Trading volumes and custody balances tell more than price charts alone.
For now, the crypto market ends the quarter in credit. Gains are broad, leverage looks contained, and policy risk has passed for the moment. The hard part is holding those gains through a quieter stretch.




